Suroso Isnandar1 , Bambang Anggoro Soedjarno P.2 , Nanang Hariyanto3 , and Daniel K.F. Tampubolon4
1 Risk Management Directorate, PT PLN (Persero), Jakarta, Indonesia 2.3School of Electrical Engineering and Informatics, Institute of Technology Bandung, Bandung, Indonesia 4 Risk Management Strategic Policy Division, PT PLN (Persero), Jakarta, Indonesia suroso.isnandar@pln.co.id, bambang.anggoro@stei.itb.ac.id, nanang.hariyanto@stei.itb.ac.id, daniel.tampubolon@pln.co.id
Abstract: Rooftop solar (PLTS Atap) is reshaping Indonesia's electricity market, challenging PLN's dominance as more consumers generate their own energy. Falling solar panel prices and increasing interest in clean energy are facilitating adoption, while digitalization enhances efficiency and transparency. However, regulations set by the Ministry of Energy and Mineral Resources (ESDM) raise concerns, potentially limiting rooftop solar's full growth potential. This study focuses on the Java-Madura-Bali (Jamali) region, home to 90% of Indonesia's rooftop solar capacity. Using scenario-based modelling, it examines how different levels of Variable Renewable Energy (VRE) penetration could influence solar adoption. The ARIMA model forecasts capacity growth, while Monte Carlo simulations assess uncertainty, factoring in regulations and grid stability. The results indicate that current regulations introduce uncertainty regarding the achievement of the VRE target. In contrast, regulatory flexibility could lead to greater expansion, showing how policy decisions impact renewable energy adoption. These findings highlight the need to reassess regulations and adopt a more flexible framework that supports grid stability and growing rooftop solar demand.
Keywords: Rooftop solar penetration; energy policy; forecasting and uncertainty modelling.
1. Introduction
The rapid growth of renewable energy technologies is transforming Indonesia's electricity market. Among these, rooftop solar (PLTS Atap) are reshaping the traditional business model dominated by the state-owned utility, The National Utility Company (PLN). The declining cost of solar panels and increasing awareness of clean energy have driven rooftop solar adoption, fostering a "prosumer" culture where consumers also generate electricity. This shift challenges the single-buyer market structure, impacting market share, revenue streams, and sector stability [1,27]. However, while the momentum is building, Indonesia still faces regulatory and structural barriers that limit the full potential of rooftop PV deployment—barriers that neighbouring countries have worked to overcome.
While Indonesia is just beginning to navigate this shift, other countries in the region, such as Malaysia, offer valuable lessons. Rooftop solar has emerged as a key decarbonization tool in many countries, including Malaysia. Malaysia has implemented rooftop solar initiatives through national quota allocations—such as the 500 MW under the Net Energy Metering (NEM) 3.0 scheme—and streamlined interconnection procedures. These measures have significantly accelerated rooftop solar adoption and reinforced the country's commitment to a low-carbon energy future [30]. On the other hand, The Indonesian Ministry of Energy and Mineral Resources (ESDM) has established a quota for the development of rooftop solar systems for the period 2024 to 2028. This initiative aims to promote the adoption of renewable energy and reduce reliance on fossil fuels. The total allocated quota over these five years is 5,045 megawatts (MW), The implementation of this quota system is outlined in the Decree of the Director General of Electricity Number 279.K/TL.03/DJL.2/2024, which provides detailed allocations across eleven power systems in Indonesia. For instance, the Java-Madura-Bali region receives the largest portion, reflecting its high energy demand and potential for solar energy utilization. In this
Received: February 5th, 2025. Accepted: March 25th, 2025
DOI: 10.15676/ijeei.2025.17.1.1
context, the role of PT PLN (Persero) as the sole electricity off-taker in Indonesia becomes increasingly complex. As a vertically integrated utility operating under a single-buyer framework, PLN must navigate the challenge of maintaining grid stability, securing financial viability, and simultaneously supporting the national agenda for renewable energy expansion. While the quota system aims to ensure controlled integration of rooftop PV into the grid, it also imposes limitations on the capacity that can be installed each year. This constraint may unintentionally deter the participation of residential prosumers and private investors, who face uncertainty regarding project approvals and connection timelines. Such limitations could potentially slow down-market growth and reduce the attractiveness of rooftop solar investments in the absence of complementary regulatory incentives.
China, the United States, Japan, India, and Germany have each adopted distinct policy measures to support solar energy development. These include feed-in tariffs (FITs), investment tax credits, net metering, competitive auctions, and direct subsidies. China and India have focused on large-scale capacity targets backed by subsidies and auctions. The U.S. promotes solar through federal and state incentives, including tax credits and net metering. Japan has utilized FITs and introduced floating PV to address land constraints. Germany transitioned from FITs to auctions under its Renewable Energy Act. Overall, these policies have enabled significant growth in solar PV capacity and provide useful models for other nations pursuing energy transitions [33].
According to Indonesia's Ministry of Energy and Mineral Resources (ESDM), from 2018 to January 2024, rooftop solar has grown at a compound annual growth rate (CAGR) of 69.38%, with installed capacity increasing by 134.26% [2]. This substantial growth reflects a shift in energy consumption patterns and further reinforces the role of rooftop solar as a market disruptor. On the other hand, Bloomberg data shows a decline in solar panel prices from 2017 to 2023, while during the same period there has been an increase in installed rooftop solar capacity (shown in Fig.1) [3,26]. These figures suggest that Indonesia has only begun to tap into this vast potential. With the continued decline in panel costs, supportive regulatory frameworks, and growing public awareness, rooftop solar is well-positioned to become a key pillar of Indonesia's clean energy future. Moreover, the study estimates that rooftop solar could contribute up to 19% of Indonesia's total electricity needs by 2050, underscoring the strategic importance of expanding rooftop installations, particularly in urban and peri-urban areas [31]. The growing adoption of rooftop solar is a global phenomenon. Rising electricity demand, price volatility, and climate concerns have accelerated the shift toward solar photovoltaic systems. Rooftop solar plays a key role in this transition, particularly in countries like China, the US, Germany, and India, where policy support has driven large-scale adoption. These cases highlight the importance of regulatory frameworks in enabling RSPV deployment. Building on these insights, this study analyses Indonesia's rooftop solar outlook using ARIMA forecasting and Monte Carlo simulation to assess capacity growth under existing policy constraints [29].
Rooftop solar adoption has triggered structural shifts, particularly in densely populated regions like Java-Madura-Bali (Jamali), where most installations are concentrated. This transition presents both opportunities and challenges for industry stakeholders, as traditional utilities face growing competition from decentralized energy sources. The rise of private and international solar providers has further intensified market competition, altering electricity supply and demand dynamics.
Beyond market competition, the operational challenges posed by rooftop solar disruption introduce complexity into power system management. PLN must navigate a multi-objective optimization process across different sectors while considering multiple constraints, such as grid stability, financial sustainability, and regulatory compliance. The integration of distributed generation requires strategic planning to maintain reliability, balance electricity supply and demand, and ensure grid resilience amidst shifting consumption patterns [4].
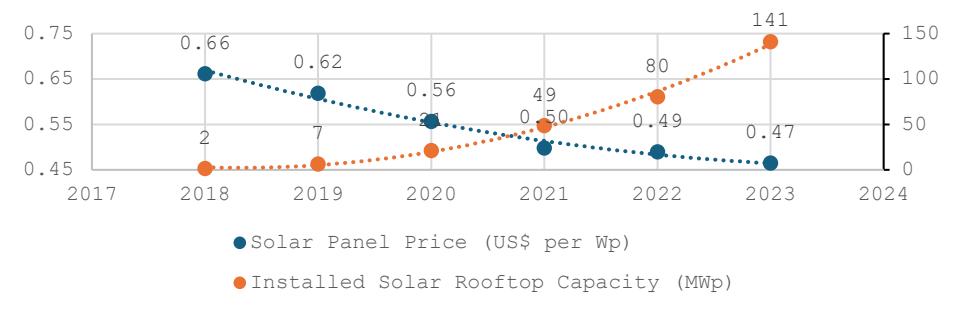
Figure 1. Rooftop Solar Power Plant Capacity and Price Trendline
In recent years, digital transformation has become a key driver in the development of renewable energy in Indonesia. Ministerial Regulation of Energy and Mineral Re-sources No. 26/2021 represents a significant milestone in the nation's energy policy by mandating that State-Owned Enterprises (BUMN) holding the IUPTLU license develop a digital application to manage rooftop solar in an integrated manner [5]. This application not only connects with Supervisory Control and Data Acquisition (SCADA) systems or distribution smart grids but also integrates with several systems managed by PLN, including Enterprise Asset Management (EAM), Geo-graphic Information System (GIS), and Customer Management Software. Such integration is expected to yield more accurate costing capacity calculations that reflect real operational conditions in the field, while simultaneously enhancing transparency for all stakeholders [6,28].
Even though solar panel prices are declining, and digitalization is advancing, regulatory constraints—specifically the quota imposed by the Ministry of Energy and Mineral Resources (ESDM)—present a notable challenge. While these economic and technological trends are expected to drive broader solar energy adoption, the quota, established to ensure grid stability, may ultimately restrict further market penetration [7]. This paper critically examines the balance between market-driven growth and regulatory limitations, highlighting the need for policy adjustments that can reconcile grid reliability with the accelerated deployment of solar energy systems.
This study contributes to a broader understanding of how state-owned utilities can adapt to disruptive energy transitions while maintaining financial sustainability and service reliability. Based on the potential disruption, this study explores the capacity of rooftop solar in the Jamali region under PLN's transformation toward Net Zero Emission (NZE) 2060. The modelling aims to project the potential fulfilment of various Variable Renewable Energy (VRE) penetration scenarios—low, moderate, and high—by 2028, while also estimating how rooftop solar capacity quotas contribute to regulations under the single-buyer mechanism. It provides insights into PLN's strategic responses, regulatory challenges, and the evolving competitive dynamics of Indonesia's electricity sector.
2. Methods
Jamali was selected as the primary research area for investigating rooftop solar dynamics due to its overwhelming representation of Indonesia's renewable energy landscape. The Java-Madura-Bali (Jamali) System contributes approximately 90.07% of the nation's total installed rooftop solar capacity (shown in Fig.2) and accounts for 61% of the customer base in terms of both number and installed capacity. This concentrated market provides an ideal setting for analyzing adoption patterns, operational performance, and the impacts of policy interventions. By focusing on Jamali, the research aims to uncover insights that not only reflect the region's unique energy dynamics but also inform broader strategies for scaling rooftop solar power nationwide.
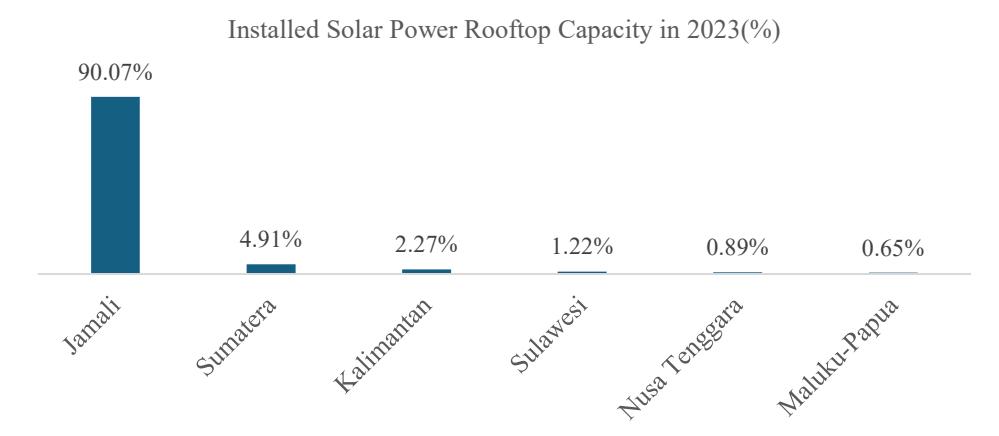
Figure 2. Installed Solar Power Rooftop Capacity in 2023
This study forecasts the penetration of rooftop solar based on penetration scenarios for Variable Renewable Energy (VRE), categorized as Low (4,000 MW), Moderate (6,000 MW), and High (8,000 MW), with a maximum penetration target of 25% of the peak load. The High scenario, derived from 25% of the peak load, corresponds to 7,950 MW [8], which has been proven to be conducted under power system optimization constraints, including a power mismatch limit of ≤1%, a spinning reserve of ≥1,000 MW, and a fast reserve of ≥500 MW, to ensure system reliability.
In developing the model for rooftop solar capacity in the Jamali region, several key assumptions guide the analysis. First, the baseline is set at 118.67 MW of installed solar capacity in 2023, encompassing both rooftop solar and utility scale owned by PLN and independent power producer (IPP) projects. Second, the planned commercial operation dates (COD) of solar power plants in Java-Madura-Bali from 2024 to 2028, as outlined in the Electric Power Supply Business Plan Draft (RUPTL) 2024–2033, are treated as fixed variables. Third, the ARIMA forecasting method is applied to project additional rooftop solar installations for the 2024–2028 period, as it is particularly effective in forecasting time series data with trends and autocorrelations [9]. Finally, quota allocations issued by the Ministry of Energy and Mineral Resources (ESDM), through the Directorate of Electricity, provide an essential regulatory reference for capacity growth.
To estimate the total installed capacity of solar power plant in the Jamali region from 2025 to 2028, we begin by considering the existing capacity baseline, the planned additions outlined in the RUPTL, and projections of rooftop solar installations. By combining these components, we obtain a clear forecast of the expected total capacity in 2028, as shown in Equation 1.
Solar Capacity2028 = Existing Solar Capacity + \[\sum_{t=2024}^{2028} (\Delta Utility Solar Addition_t + \Delta Rooftop Solar_t)\] (1)
Where:
- represents the installed capacity of all types solar power plant as of 2023 in Java-Madura-Bali grid, set at a baseline of 118.67 MW.
- ∆ is the annual addition to utility scale solar power plant from PLN and IPP, as outlined in the RUPTL for year.
- ∆ refers to the annual increase in rooftop solar capacity for year. This variable is calculated using a specific forecasting method (ARIMA) based on historical data of annual rooftop solar additions since 2012.
A forecasting approach was applied to annual capacity addition data to predict solar rooftop penetration, and among the methods tested, the Auto Regressive Integrated Moving Average (ARIMA) model proved most suitable for several reasons. First, the input data consists of annual time series without a seasonal component, making ARIMA well-suited for capturing trends and autocorrelations [10]. ARIMA models are particularly effective for modelling non-stationary time series data by differencing to achieve stationarity, which is applicable in this context (Kinney, 1978) [11]. Second, ARIMA can be calibrated through its three parameters—(p, d, q)—to effectively capture data patterns and enhance statistical accuracy. Third, being grounded in robust statistical theory, ARIMA can generate forecasts accompanied by confidence intervals or specific percentiles, thus facilitating risk-based decision-making [12]. Moreover, model evaluation showed that metrics such as Mean Absolute Percentage Error (MAPE), Theil's U, and Durbin-Watson fell within acceptable thresholds, further highlighting ARIMA's reliability. The mathematical equation of ARIMA (p, d, q) [13] is shown in Equation 2.
\[\Delta^{d} y_{t} = \sum_{i=1}^{p} \phi_{i} \Delta^{d} y_{t-i} + e_{t} + \sum_{j=1}^{q} \theta_{j} e_{t-j}\] (2)
Where:
- \(\Delta^d y_t\) is the data that has been differenced d times
- \(\phi_i\) is the autoregressive (AR) coefficient
- \(e_t\) is the moving average (MA) coefficient
- \(\theta_i\) is the number of past values (lags) for AR
- p is the number of differencing operations for I
- q is the number of past errors for MA
The use of the ARIMA method requires determining of the main component orders, namely Autoregressive (p), Integrated (d), and Moving Average (q), where typically begins with ensuring that the original time series is stationary. This is accomplished through formal stationarity tests, the Augmented Dickey-Fuller (ADF) test, which evaluates the presence of a unit root. If the time series is found to be non-stationary, differencing is applied successively until the series becomes stationary. In this case, the test results indicated the necessity of performing three rounds of differencing, thus setting the differencing order at d=3. This choice ensures that the series is rendered suitably stationary without incurring the drawbacks associated with excessive differencing.
Following the determination of the differencing order, the next steps are selecting the moving average order (q) using the autocorrelation function (ACF) and the autoregressive order (p) using partial autocorrelation function (PACF). In this case, the moving average analysis points to a single lag being necessary for capturing the short-term dependencies, leading to q=1. Conversely, the data suggest that no autoregressive terms significantly improve the model fit, resulting in p=0. Thus, the finalized ARIMA model for this case is ARIMA (0,3,1).
Forecast \(\Delta PLTS_{Atap,t}\) has a Standard Error (SE) represented by a normal distribution according to the ARIMA (0,3,1) formula shown in Equation 3.
\[SE(y_t) = \sqrt{\sigma_e^2 [1 + \phi_1^2 + \theta_1^2]}\] (3)
Where:
- \(\sigma_e^2\): Variance of the residual (white noise error)
- \(\phi_1^2\): Variance contribution from the AR (1) term
- \(\theta_1^2\): Variance contribution from the MA (1) term
The Root Mean Square Error (RMSE) is a standard method to measure the error of a model in predicting data. It represents the average magnitude of prediction errors in a model, with lower values indicating better fit. However, there is not a universally accepted RMSE value, as its acceptability depends on the specific context and scale of the data. Mathematically, RMSE is expressed in Equation 4.
Suroso Isnandar, et al.
\[RMSE = \sqrt{\frac{1}{n} \sum_{i=1}^{n} (y_i - \hat{y}_i)^2}\] (4)
Where:
y<sub>i</sub>: observed values
• \(\hat{y}_i\): predicted value
• n: total number of observations
Mean Absolute Percentage Error (MAPE) is a commonly used statistical measure to evaluate the accuracy of a forecasting model. It indicates the average absolute error as a percentage of the actual value, which is useful for assessing how far the forecast results deviate (in percentage terms) from the actual values [12,14] (see Equation 5).
\[MAPE = \frac{1}{n} \sum_{t=1}^{n} \left| \frac{y_t - \hat{y}_t}{y_t} \right| \times 100\%\]
Where:
• \(y_t\) is the actual (observed) value at the t-th data point,
• \(\hat{y}_t\) is the forecast (predicted) value at the t-th data point,
• n is the number of data points.
The MAPE percentage result can be grouped according to typical criteria interpreted [12,15] as follows:
MAPE < 10%: Highly accurate</li>
• MAPE 10%–20%: Good accuracy
• MAPE 20%–50%: Moderate accuracy
• MAPE > 50%: Inaccurate
Theil's U is a statistical measure used to evaluate the accuracy of a forecasting model by comparing its performance to a simple (naïve) model, such as one that predicts future values solely based on the previous value. Theil's U has been widely applied in economic and financial forecasting to assess model efficiency and predictive accuracy [16,17]. This statistic provides insight into whether a more complex forecasting model is superior to a simpler approach. The formula for Theil's U [13] is given in Equation 6.
\[Theil's \; U = \frac{\sqrt{\frac{1}{n} \sum_{t=1}^{n} (y_t - \hat{y}_t)^2}}{\sqrt{\frac{1}{n} \sum_{t=1}^{n} {y_t}^2 + \sqrt{\frac{1}{n} \sum_{t=1}^{n} \hat{y}_t}^2}}\]
Where:
• \(y_t\) is the actual (observed) value at the t-th data point,
• \(\hat{y}_t\) is the forecast (predicted) value at the t-th data point,
• n is the number of data points.
The interpretation of Theil's U can be categorized as follows [18]:
• Theil's U < 1: The forecasting model is better than the naïve model.
• Theil's U = 1: The forecasting model performs on par with the naïve model.
• Theil's U > 1: The forecasting model is worse than the naïve model.
Durbin-Watson is a statistic used to detect residual autocorrelation in a regression model. Autocorrelation refers to the relationship between residuals (errors) in successive observations.
This statistic is crucial for assessing whether the residuals are independent in regression analysis. The Durbin-Watson formulation [13] is shown in Equation 7 and Equation 8.
\[DW = \frac{\sum_{t=2}^{n} (e_t - e_{t-1})^2}{\sum_{t=1}^{n} e_t^2}\] \[e_t = y_t - \hat{y}_t\]
Where:
- \(e_t\) is the residual at time t (the difference between the actual value and the predicted value),
- \(y_t\) is the actual (observed) value at the t-th data point,
- \(\hat{y}_t\) is the forecast (predicted) value at the t-th data point,
- n is the number of data points.
The interpretation of the Durbin-Watson value can be categorized as follows:
- DW ≈ 2: No autocorrelation.
- DW < 2: Positive autocorrelation.
- DW > 2: Negative autocorrelation.
- DW = 0: Perfect positive autocorrelation.
- DW = 4: Perfect negative autocorrelation.
To ensure that the ARIMA (0,3,1) method is the best method of the available options, statistical testing is carried out on several forecast methods including ARIMA with different orders (typical orders). Furthermore, the statistical results of the forecast accuracy are compared with each other and with the benchmark values as explained above. The forecast methods tested are:
- ARIMA (0,3,1)
- ARIMA (1,2,1)
- ARIMA (1,1,1)
- Single Exponential Smoothing
- Double Exponential Smoothing
- Single Moving Average
- Double Moving Average
- Damped Trend Non-Seasonal
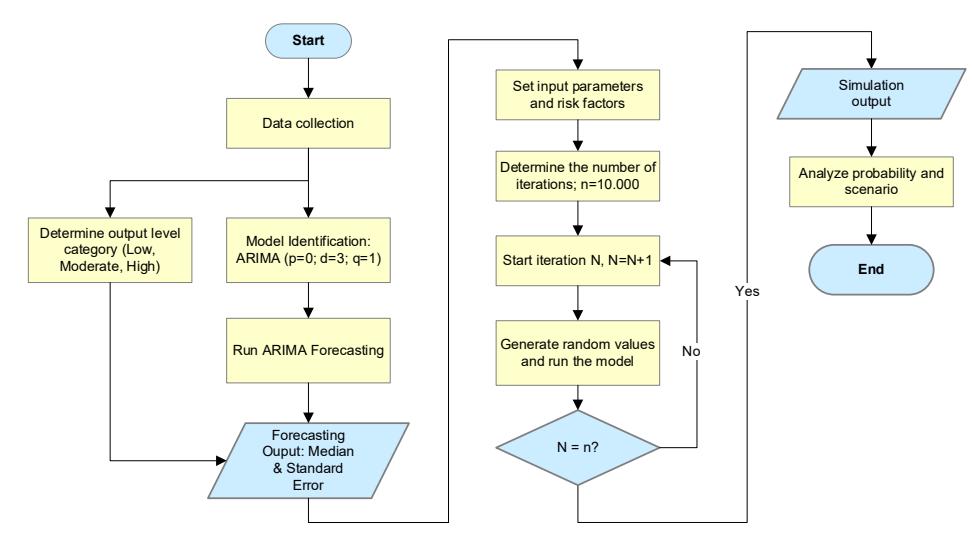
Figure 3. ARIMA Forecast and Monte Carlo Simulation Stages
In this study, the model uses the previously presented Java-Madura-Bali (Jamali) solar PV formula for 2028 (in MW) from Eq. (1), incorporating the forecasted, normally distributed rooftop solar capacity increment (2025–2028) as the primary risk factor. A 10,000-iteration simulation—classified as high-precision for complex cases [23]—yields various installed capacity scenarios in 2028, depicted in a histogram. This approach offers probability estimates for each VRE scenario, including the 5th and 95th percentiles reflecting extreme outcomes.
3. Results
A. Results of the Installed Solar PV Capacity Modelling in the Java-Madura-Bali System The accuracy statistics of the forecast results using 8 methods are compared and ranked to select the best method. In addition, the accuracy statistics are also compared with the benchmark value as validation of the selected method. The ranking results shown in Table 1 reveals that the ARIMA (0,3,1) method is the best forecast method, and meets the established benchmark criteria.
| Methods | Accuracy Statistics | ||||
|---|---|---|---|---|---|
| Rank | RMSE | MAPE | Theil's U | Durbin Watson | |
| 1 | ARIMA (0,3,1) | 12.66 | 19.87% | 0.7942 | 1.7573 |
| 2 | ARIMA (1,2,1) | 13.00 | 25.78% | 2.1641 | 1.4686 |
| 3 | ARIMA (1,1,1) | 18.32 | 39.83% | 8.3390 | 0.5214 |
| 4 | Double Exponential Smoothing | 24.40 | 47.83% | 0.9616 | 0.4245 |
| 5 | Damped Trend Non-Seasonal | 24.41 | 47.85% | 0.9616 | 0.4245 |
| 6 | Double Moving Average | 35.83 | 62.24% | 0.7950 | 0.4773 |
| 7 | Single Moving Average | 36.84 | 81.58% | 1.0000 | 0.4376 |
| 8 | Single Exponential Smoothing | 36.86 | 81.62% | 1.0001 | 0.4376 |
| Benchmark threshold (accuracy reference) | Lower is Better | <20% | <1 | ≈2 ± 0.5 | |
The forecasting results using the ARIMA (0,3,1) method are supported by statistical indicator analysis, demonstrating robust validity and accuracy. A Durbin-Watson test value of 1.76 indicates that the model is nearly free from significant autocorrelation, making it reliable for forecasting. Furthermore, a Theil's U value of 0.79—within the range of 0.5 to 1—suggests the model's predictions are fairly accurate compared to naive forecasts. Meanwhile, the Root Mean Square Error (RMSE) of 12.66 implies a very small margin of error, approximately 1% relative to the maximum projection of 1,279 MW (shown in Fig.4). Collectively, these indicators confirm that the ARIMA (0,3,1) method can produce reliable and accurate forecasts, aligning well with the projected data characteristics. The forecasting results using ARIMA (0,3,1) yield an output comprising a median value and a measured standard error deviation, as follows:
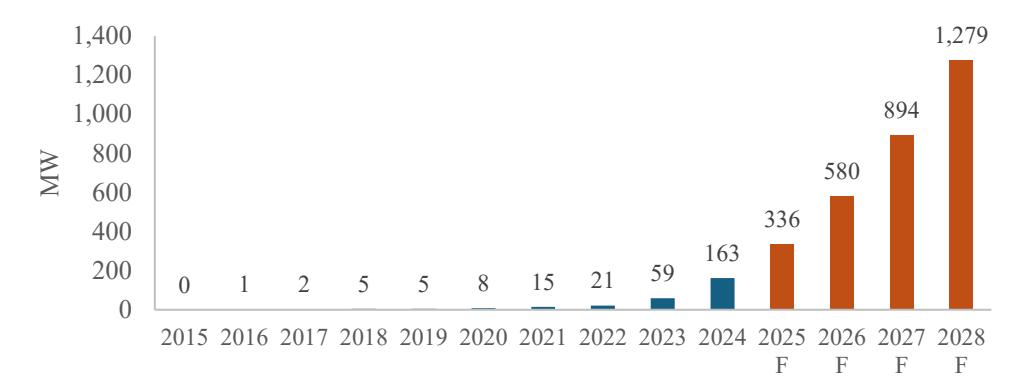
Figure 4. Realization and Forecast of Rooftop Solar Power Capacity in Jamali System
| Year | Forecasted Additional Rooftop Solar Capacity (MW), Median/Mean | Forecasted Additional Rooftop Solar Capacity (MW), Standard Error (SE) |
| 2025 | 336.22 | 12.66 |
| 2026 | 580.12 | 51.24 |
| 2027 | 894.26 | 122.21 |
| 2028 | 1,278.64 | 231.46 |
Table 2. Forecasted Additional Rooftop Solar Capacity (MW) in the Java-Madura-Bali System
According to Table 2, The forecast results indicate that the penetration of rooftop solar is experiencing a bullish trend that continues to rise consistently, even displaying a growth pattern similar to an exponential trend. The forecast results are also consistent with the realization of rooftop solar power growth in the US in the 2011-2014 period (shown in Fig.5) [21]. This suggests a significant uptick in rooftop solar adoption, likely influenced by various factors such as growing awareness of renewable energy, government incentives, and decreasing solar panel technology costs. The trend points to a positive outlook for the future development of rooftop solar, with an increasing potential to support the clean energy transition and meet national renewable energy capacity targets. However, this exponential-like growth pattern also underscores the need for proactive measures to maintain the system's sustainability, both from the standpoint of supporting infrastructure and related policies.
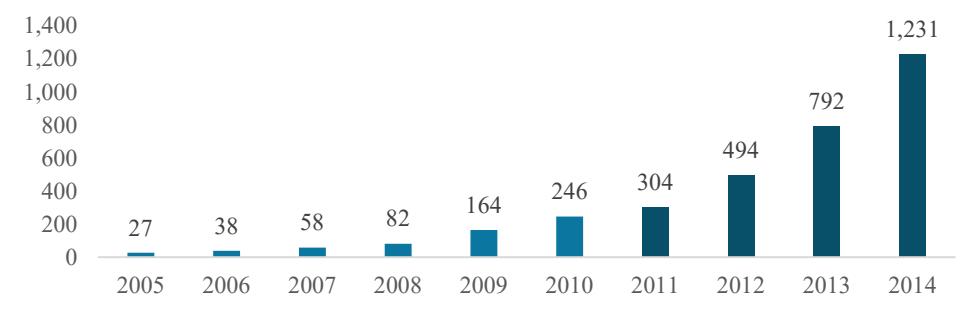
Figure 5. Annual solar PV capacity installations in the U.S. residential sector (MW)
B. Modelling Results of Solar PV Penetration in the Java-Madura-Bali System with a Rooftop Solar Quota
According to Table 3 below, the baseline data represents the solar PV installed capacity as of 2023. The RUPTL data, on the other hand, outlines the planned expansion from 2024 onward, including both solar PV designated for decentralized use and those allocated under the Java-Bali quota. Cumulative rooftop solar PV with quota restrictions will begin to be implemented in 2026, where the cumulative forecast of 1,197.56 MW has already exceeded the quota of 910 MW.
The projected installed rooftop solar PV capacity up to 2028 is 1,400.00 MW, while the projected penetration—including the addition of IPP solar PV—reaches 3,077.67 MW in 2028 (shown in Fig.6). This scheme indicates that the Low VRE (Variable Renewable Energy) Penetration Scenario (4,000 MW) is still far from being achieved within the next four years.
| Year | Baseline | Cumulative COD of Solar PV as per | Installed Capacity of Rooftop Solar PV | Rooftop Solar PV Quota from | Total Solar PV Capacity with |
| RUPTL | with Quota (MW) | Government (MW) | Rooftop Quota (MW) | ||
| a | b | c | d | e | f = b + c + d |
| 2024 | 118.67 | 212.00 | 281.22 | 825.00 | 493.22 |
| 2025 | 118.67 | 725.00 | 617.44 (F) | 900.00 | 1,342.44 |
| 2026 | 118.67 | 848.00 | 910.00 (Q) | 910.00 | 1,876.67 |
2027 118.67 1,049.00 1,010.00 (Q) 1,010.00 2,177.67 2028 118.67 1,559.00 1,400.00 (Q) 1,400.00 3,077.67
Table 3. Solar PV Capacity with Quota for the Years 2025–2028.
| W) | 10,000 | |||
|---|---|---|---|---|
| M | 8,000 | 8,000 | ||
| Installed Capacity ( | 6,000 | 6,000 | Forecast Low | |
| 4,000 | 4,000 | Moderate | ||
| 2,000 | High | |||
| 0 | 2023 2024 2025 F 2026 F 2027 F 2028 F |
Figure 6. Solar PV System Penetration in Java-Madura-Bali with Quota
C. Modelling Results of Solar PV Penetration in the Java-Madura-Bali System Without a Rooftop Solar Quota
According to the modelling of solar PV penetration in the Java-Madura-Bali system without a rooftop solar quota, the projected installed rooftop solar PV capacity is expected to reach 3,287.29 MW by 2028. When combined with additional IPP solar PV installations, the overall penetration is projected to reach 4,929.46 MW by that year. This analysis indicates that achieving the Low to Moderate VRE Penetration Scenario of 6,000 MW remains a realistic target within the next four years (shown in Fig.7).
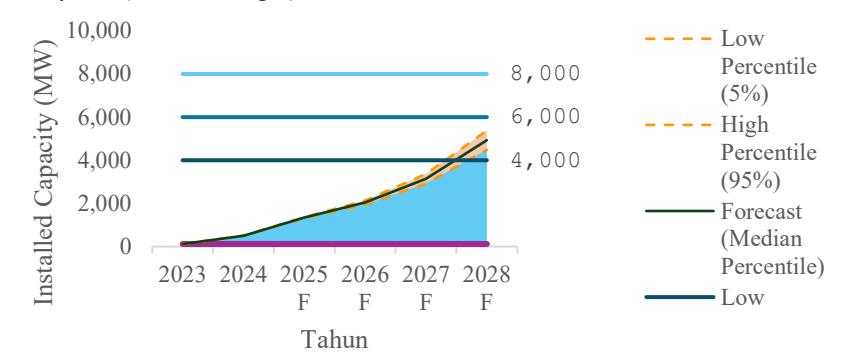
Figure 7. Solar PV Penetration in the Java-Madura-Bali System without Quota based on Low Median High Percentile.
Calculating uncertainty values is crucial for understanding risks, enhancing reliability, and supporting informed decision-making amid system complexities. To assess the uncertainty in the VRE penetration model, the simulation results are presented at the 5th and 95th percentile confidence levels. These values were obtained after performing 10,000 iterations using a Monte Carlo simulation. Below are the probability levels for the median and each percentile:
Table 4. Median, Low Percentile, and High Percentile Probabilities.
| Year | Probabilities | Installed Solar Capacity (MW) |
| Low Percentile (5%) | 4,484.23 | |
| 2028 | Median | 4,929.46 |
| High Percentile (95%) | 5,274.23 |
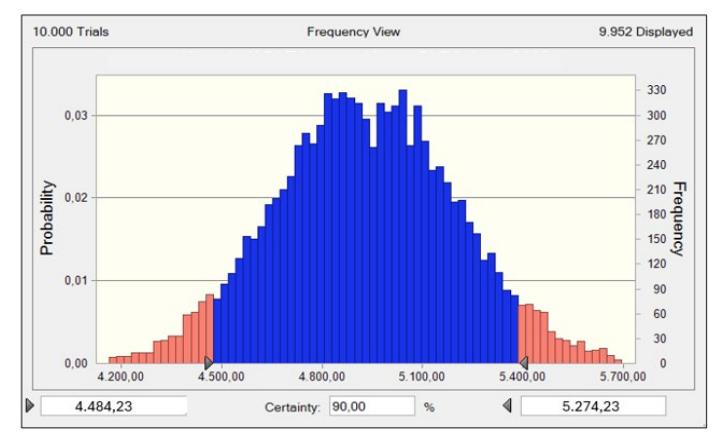
Figure 8. Solar PV Penetration in the Java-Madura-Bali System Without Quota.
According to Table 4, it can be concluded that the installed solar PV capacity under the low VRE penetration scenario (4,000 MW) has already been exceeded, even at the 5% confidence level (shown in Fig.8). This means that it is highly likely that this minimum target will be achieved or surpassed.
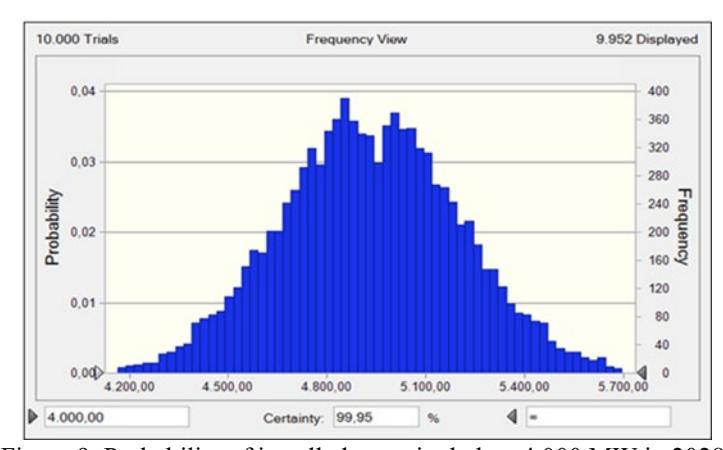
Figure 9. Probability of installed capacity below 4,000 MW in 2028.
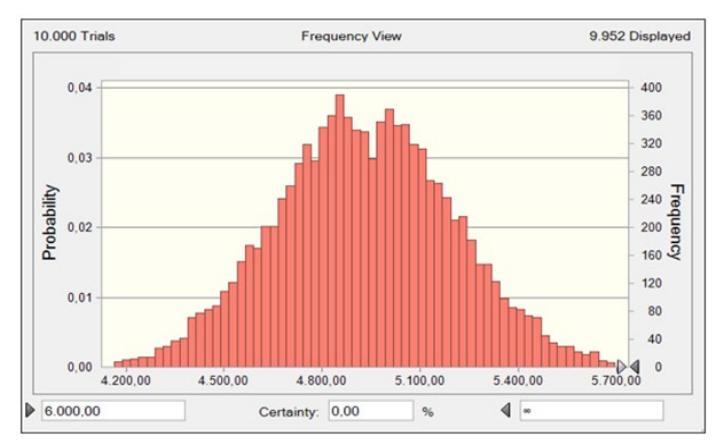
Figure 10. Probability of installed capacity between 4,000 MW and 6,000 MW in 2028.
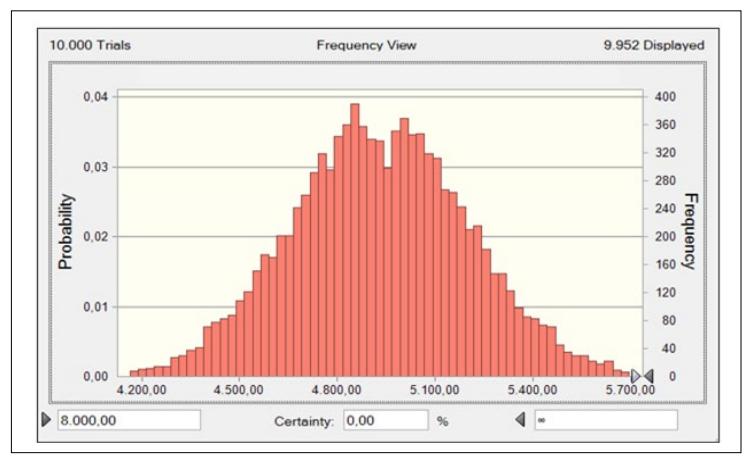
Figure 11. Probability of installed capacity above 6,000–8,000 MW in 2028.
The simulation results indicate the following cumulative probabilities:
- A 99.85% probability at a capacity of 4,000 MW, suggesting that the Low-level penetration is almost certain to be achieved, as shown in Fig.9.
- A 0.01% probability at a capacity of 6,000 MW, indicating that the Moderate-level penetration has a very small chance of being achieved, as shown in Fig.10.
- A 0.01% probability at a capacity of 8,000 MW, implying that the High-level penetration has a very small chance of being achieved, as shown in Fig.11.
4. Discussions
The implementation of PERMEN ESDM 02/2024 introduces both op-opportunities and challenges for PLN in managing the expansion of rooftop solar. The regulation enables controlled growth, ensuring alignment with grid capacity and preventing potential disruptions from micro IPPs [24]. Additionally, it opens up new business avenues, such as virtual power plants and energy storage (BESS), while integrating the financial impact of parallel operations into PLN's base energy supply costs.
However, PLN also faces several challenges, particularly revenue losses as more consumers generate their own electricity, reducing dependency on the grid. To comply with the regulation, PLN must invest in advanced meters, smart grids, and SCADA systems, while also developing a rooftop solar digital application roadmap within a limited timeframe. Furthermore, uncertainties surrounding renewable energy ownership (EBET mix) and carbon valuation pose additional complexities in PLN's long-term energy planning.
Due to the change in the electricity market, ESDM has introduced a quota system as a regulatory mechanism to manage the growth of rooftop solar. This approach aims to balance system reliability and the integration of renewable energy while ensuring a structured expansion of rooftop solar capacity. The Keputusan Direktur Jenderal Ketenagalistrikan No. 279.K/TL.03/DJL.2/2024 outlines the quota allocations from 2024 to 2028, regulating the capacity additions for different regions (Direktorat Jenderal Ketenagalistrikan, 2024) [25]. For the Java-Madura-Bali (Jamali) system, which dominates rooftop solar installations in Indonesia, the quota is set at 825 MW in 2024, 900 MW in 2025, 910 MW in 2026, 1,010 MW in 2027, and 1,400 MW in 2028.
PLN has responded to the implementation of PERMEN ESDM 02/2024 by streamlining the rooftop solar integration process through PLN Mobile. This initiative simplifies the approval and connection procedures, making it easier for customers to adopt rooftop solar while ensuring compliance with regulatory requirements. Through PLN Mobile, customers can submit applications, and the system automatically calculates the available rooftop solar quota based on real-time data. The process includes permit approval, where PLN verifies administrative and technical documents within seven days and provides a final decision within 30 calendar days. Once approved, customers sign a Power Purchase Agreement (PPA) that aligns with PERMEN ESDM 02/2024 before PLN proceeds with the grid connection and installation of advanced meters. This digital approach enhances transparency, efficiency, and accessibility in rooftop solar adoption. By automating the quota calculation and integrating the approval process into a single platform, PLN ensures that the regulatory framework is implemented effectively while maintaining grid stability. However, the success of this initiative will de-pend on how well it adapts to increasing demand and whether further refinements are needed to accommodate future policy adjustments. As of December 2023, the number of approved applications reached 3,709, with an additional 774 still in progress, reflecting strong and growing interest in rooftop solar. In terms of capacity, 262.50 MWp of rooftop solar installations have been approved, with 119.27 MWp under review, while 97.27 MWp was rejected due to technical or regulatory challenges. This surge in applications demonstrates the increasing role of rooftop solar in Indonesia's energy landscape, driven by lower solar panel costs, digitalization, and regulatory support.
Despite efforts to facilitate rooftop solar adoption, several challenges remain in ensuring seamless integration into the electricity system. Key concerns include operational risks from shifting load patterns, financial risks due to declining electricity demand, policy uncertainties regarding quota approvals, and customer-related issues such as service accessibility and monitoring delays. To mitigate these risks, operational procedures are being revised to manage load fluctuations, while financial mechanisms are being developed to address compensation needs. Policy coordination with regulators is crucial for aligning quotas with energy targets, and enhanced monitoring systems will improve transparency in rooftop solar implementation. Additionally, supporting regulations are being considered to strengthen infrastructure and service reliability. Addressing these challenges will help optimize rooftop solar growth, ensuring grid stability, financial sustainability, and long-term contributions to Indonesia's renewable energy transition.
Based on forecasting and simulation results, quota regulations play a critical role in shaping the adoption trajectory of rooftop solar in Indonesia. Under the current quota framework, the Low Variable Renewable Energy (VRE) penetration scenario of 4,000 MW in the Java-Madura-Bali (Jamali) System is unlikely to be achieved by 2028. In contrast, without a quota, the target is projected to be met with 99.85% probability, reaching a median installed capacity of 4,929.46 MW. This considerable difference underscores the impact of quota restrictions on rooftop solar growth potential.
While the quota helps regulate renewable energy integration by maintaining grid stability and supply-demand balance, the findings suggest that if not adjusted to reflect market and technological advancements, it may hinder rooftop solar expansion rather than facilitate it. Instead of acting solely as a safeguard, a rigid quota could become a constraint, limiting the sector's market-driven potential. By contrast, a non-quota scenario offers greater flexibility,
enabling the market to respond dynamically to declining costs, technological progress, and increasing consumer demand. A more adaptive regulatory approach, such as periodic reviews and adjustments, could better align with Indonesia's renewable energy goals. Rather than imposing fixed constraints, a flexible quota system would support higher rooftop solar adoption while ensuring grid reliability and long-term energy sustainability.
5. Conclusion
The results of the modelling on rooftop solar penetration within the Java-Madura-Bali (Jamali) system under a no-quota scenario indicate a projected installed capacity of 4,929.46 MW by 2028, with a high probability level of 99.85%. This finding suggests that the market dynamics in the region align with the Low to Moderate Variable Renewable Energy (VRE) Penetration scenario. Given this projection, increasing the development quota for Rooftop Solar PV emerges as a strategic policy measure to facilitate further integration of VRE into the electricity grid.
Furthermore, as the adoption of Rooftop Solar PV by consumers continues to grow, it is crucial to reassess and optimize the hosting capacity across Indonesia's power grid infrastructure. Ensuring adequate hosting capacity is essential for maintaining grid stability and accommodating the increasing penetration of decentralized renewable energy sources. This reassessment should consider technical, economic, and regulatory factors to support an efficient and sustainable energy transition.
To enhance the robustness of future research and policy recommendations, it is also necessary to expand the scope of analysis beyond the Java-Madura-Bali system. Conducting similar modelling studies in other regions across Indonesia would provide a more comprehensive understanding of regional variations in grid capacity, solar energy potential, and consumer adoption patterns. By incorporating diverse geographical and infrastructural conditions, future studies can generate more representative insights that align with real-world conditions, ultimately guiding more effective policy and investment decisions for Rooftop Solar PV development at the national level.
6. References
- [1]. Energy Tracker Asia. (2023). Solar Energy in Indonesia: Current State and Future Outlook. Retrieved from https://energytracker.asia/solar-energy-indonesia/ (Accessed on March 9, 2025).
- [2]. ESDM. (2024). PLTS Atap Kaya Potensi Amankan Investasi, Kunci Bauran Energi. Indonesia's Ministry of Energy and Mineral Resources. Retrieved from https://www.esdm.go.id/en/media-center/news-archives/plts-atap-kaya-potensi-amankaninvestasi-kunci-bauran-energi (Accessed on March 9, 2025).
- [3]. BloombergNEF. (2023). 2H 2023 Levelized Cost of Electricity (LCOE) Update: An Uneven Recovery. BloombergNEF. Retrieved from https://about.bnef.com/blog/2h-2023 lcoe-update-an-uneven-recovery/ (Accessed on March 9, 2025).
- [4]. Institute for Essential Services Reform (IESR). (2024). Indonesia Energy Transition Outlook 2025.
- [5]. Ministry of Energy and Mineral Resources. (2021). Ministerial Regulation No. 26 of 2021 on Rooftop Solar Power Plants Connected to the Power Grid of Business License Holder for Public Power Supply. Retrieved from https://setkab.go.id/en/energy-minister-issuesregulation-on-rooftop-solar-power-plants/ (Accessed on March 9, 2025).
- [6]. COPA-DATA. (2023). The Role of GIS and SCADA in Energy. Retrieved from https://www.copadata.com/en/industries/energy-infrastructure/energy-insights/gis-scadazenon/ (Accessed on March 9, 2025).
- [7]. Reccessary. (2024). Indonesia Sets Quotas for Rooftop Solar Deployment to 5.7 GW by 2028. Retrieved from https://www.reccessary.com/en/news/id-regulation/indonesia-setsquotas-for-rooftop-solar-deployment-to-5-7-gw-by-2028 (Accessed on March 9, 2025).
- [8]. Isnandar, S., Simorangkir, J. F., Banjar-Nahor, K. M., Paradongan, H. T., & Hariyanto, N. (2024). A multiparadigm approach for generation dispatch optimization in a regulated electricity market towards clean energy transition. Energies, 17(15), 3807. https://doi.org/10.3390/en17153807
- [9]. Shumway, R.H.; Stoffer, D.S. Time Series Analysis and Its Applications: With R Examples, 4th ed.; Springer: New York, NY, USA, 2017.
- [10]. Maravall, A., & Gómez, V. (1994). Estimation, Prediction, and Interpolation for Nonstationary Series with the Kalman Filter. Journal of the American Statistical Association, 89(426), 611-624.
- [11]. Kinney, W. R. (1978). ARIMA and Regression in Analytical Review: An Empirical Test. The Accounting Review, 53(1), 48-60.
- [12]. Hyndman, R.J.; Athanasopoulos, G. Forecasting: Principles and Practice; OTexts: Melbourne, Australia, 2021.
- [13]. Box, G.E.P.; Jenkins, G.M.; Reinsel, G.C.; Ljung, G.M. Time Series Analysis: Forecasting and Control, 5th ed.; Wiley: Ho-boken, NJ, USA, 2015.
- [14]. Tofallis, C. (2015). A better measure of relative prediction accuracy for model selection and model estimation. Journal of the Operational Research Society, 66(8), 1352-1362. DOI: 10.1057/jors.2014.103.
- [15]. Lewis, C. D. (1982). Industrial and business forecasting methods: A practical guide to exponential smoothing and curve fitting. London: Butterworths.
- [16]. Mizrach, B. (1992). The Distribution of the Theil U-Statistic in Bivariate Normal Populations. Economics Letters, 38(2), 163-167. Retrieved from https://ideas.repec.org/a/eee/ecolet/v38y1992i2p163-167.html (Accessed on March 9, 2025).
- [17]. Dharmasena, K., & Bessler, D. A. (2011). Weak-Form Efficiency vs. Semi-Strong Form Efficiency in Price Discovery: An Application to International Black Tea Markets. International Journal of Remote Sensing. Retrieved from https://www.researchgate.net/figure/Theils-U-Statistic-to-Compare-the-Forecast-Performance-of-VAR-in-Different-Markets_tbl5_274689152 (Accessed on March 9, 2025).
- [18]. Bhardwaj, S. B., Singh, R., & Kumar, R. (2020). A Study of Variation in Forecasting Using Theil's Statistic. International Journal of Current Microbiology and Applied Sciences, Special Issue-11, 836-843. Retrieved from https://www.ijcmas.com/special/11/S.%20B.%20Bhardwaj%2C%20et%20al.pdf (Accessed on March 9, 2025).
- [19]. Durbin, J., & Watson, G. S. (1950). Testing for Serial Correlation in Least Squares Regression, I. Biometrika, 37(3/4), 409-428.
- [20]. Durbin, J., & Watson, G. S. (1951). Testing for Serial Correlation in Least Squares Regression, II. Biometrika, 38(1/2), 159-177.
- [21]. Harrison, P.J.; Stevens, C.F. Bayesian Forecasting. Journal of the Royal Statistical Society 1976, 38, 205–247.
- [22]. Morgan, M.G.; Henrion, M. Uncertainty: A Guide to Dealing with Uncertainty in Quantitative Risk and Policy Analysis; Cambridge University Press: Cambridge, UK, 1990.
- [23]. Rubinstein, R.Y.; Kroese, D.P. Simulation and the Monte Carlo Method, 3rd ed.; Wiley: Hoboken, NJ, USA, 2016.
- [24]. Kementerian Energi dan Sumber Daya Mineral Republik Indonesia (ESDM). (2024). Peraturan Menteri Energi dan Sumber Daya Mineral Nomor 2 Tahun 2024 tentang Pembangkit Listrik Tenaga Surya Atap yang Terhubung Pada Jaringan Tenaga Listrik Pemegang Izin Usaha Penyediaan Tenaga Listrik Untuk Kepentingan Umum.
- [25]. Direktorat Jenderal Ketenagalistrikan. (2024). Keputusan Direktur Jenderal Ketenagalistrikan Nomor 279.K/TL.03/DJL.2/2024 tentang Kuota Pengembangan Sistem PLTS Atap PT Perusahaan Listrik Negara (Persero) Tahun 2024 Sampai Dengan Tahun 2028. Retrieved from https://paralegal.id/peraturan/keputusan-direktur-jenderalketenagalistrikan-nomor-279-k-tl-03-djl-2-2024/ (Accessed on March 9, 2025).
- [26]. PT PLN (Persero), Statistical Report 2023 Audited, Jakarta: PT PLN (Persero), 2024.
- [27]. PT PLN (Persero), Sustainability Report PLN 2023, Jakarta: PT PLN (Persero), 2024.
- [28]. PT PLN (Persero), Annual Report PLN 2023, Jakarta: PT PLN (Persero), 2024.
- [29]. Al-Sharafi, E. A., Alhussein, M., Ali, A., & Aurangzeb, K. (2023). Rooftop Solar PV Policy Assessment of Global Best Practices and Lessons Learned for the Kingdom of Saudi Arabia. Sustainability, 15(12), 9630. https://doi.org/10.3390/su15129630
- [30]. Setiawan, E. A., Sumarto, M. P., & Hussin, M. Z. (2024). A Lesson of Solar Energy Development in Malaysia and Indonesia. International Journal of Energy Economics and Policy, 14(1), 401–411. https://doi.org/10.32479/ijeep.15258
- [31]. Silalahi, D.F.; Blakers, A.; Stocks, M.; Lu, B.; Cheng, C.; Hayes, L. Indonesia's Vast Solar Energy Potential. Energies 2021, 14(17), 5424. https://doi.org/10.3390/en14175424.
- [32]. Directorate General of Electricity. (2024, May 27). Decree of the Director General of Electricity Number 279.K/TL.03/DJL.2/2024 on the Rooftop Solar PV System Development Quota for PT PLN (Persero) for the Years 2024 to 2028. Ministry of Energy and Mineral Resources of the Republic of Indonesia.
- [33]. Minazhova, S.; Akhambayev, R.; Shalabayev, T.; Bekbayev, A.; Kozhageldi, B.; Tvaronavičienė, M. A Review on Solar Energy Policy and Current Status: Top 5 Countries and Kazakhstan. Energies 2023, 16, 4370. https://doi.org/10.3390/en16114370.
Suroso Isnandar received his Engineering degree in Electrical Power Engineering from ITB in 1991 and received his Master of Science degree in Power and Management from the University of Abertay Dundee in 1999. He works at PT PLN (Persero) as Director of Risk Management since 2023. His current research interest is the integration of variable renewable energy in the electrical system. He can be contacted at suroso.isnandar@pln.co.id.
equipment.
Bambang Anggoro Soedjarno (Member, IEEE) received the B.Sc., M.Sc., and Ph.D. degrees from the Department of Electrical Engineering, Institut Teknologi Bandung, Indonesia, in 1979, 1990, and 2006, respectively. He is currently a Professor of the School of Electrical Engineering and Informatics, Institut Teknologi Bandung. His research interests include electromagnetics, material science, safety and electric grounding system, renewable energy environment, and risk, reliability and quality engineering, and high voltage
Nanang Hariyanto (Member, IEEE) received the B.Sc., M.Sc., and Ph.D. degrees from the Department of Electrical Engineering, Institut Teknologi Bandung, Indonesia, in 1986, 1999, and 2010, respectively. He is currently a Lector of the School of Electrical Engineering and Informatics and a Researcher with the Power System Laboratory, Institut Teknologi Bandung. His research interests include power system analysis, distributed generation, power system protection, power system stability, and renewable energy.
Daniel Karmel Fernando Tampubolon received his Bachelor of Engineering degree in Telecommunication from ITB in 2006 and received his Master of Engineering Management from Curtin University of Technology Australia in 2012. He works at PT PLN (Persero) as Executive Vice President of Strategic Policy Risk Management. His current research interests are system planning and integration of variable renewable energy in the electricity system. He can be contacted at daniel.tampubolon@pln.co.id.